Blog

Your blog category

Job vs Business Income
Blog

Job vs Business Income: What the 2026 Data Shows

A salary is priced against a role, a market rate, and a set of hours. The income a business generates is priced against something else entirely: the value it actually creates for customers, which has no fixed ceiling attached to it. Job vs business income isn’t just a philosophical distinction; it’s a measurable gap that 2025 and 2026 data has started to quantify with real precision, and the numbers explain a lot about why the two paths compound so differently over time. The Data Behind Job vs Business Income The clearest evidence comes from a large-scale study specifically built to measure this gap. Gallup’s Ownership Advantage report, fielded across 5,926 working adults in fall 2025, found that owner-employers, business owners who employ others, report a median household income of $279,000 and median net worth of $3 million, compared to a roughly $50,000 income advantage over employees and a 19-point gap in overall wellbeing. That’s not a marginal difference. It’s a structural one, and it lines up with older data showing the same pattern: the median net worth of self-employed families sits at $380,000, more than four times the $90,000 median net worth of a typical working family, according to Federal Reserve-based research on business ownership and wealth. Why a Job Pays for the Role, Not the Outcome A salary is fundamentally priced against a position, not against the specific value an individual produces in it. Two people doing the same job at the same company, one who generates modest results and one whose work quietly saves the company millions, are usually paid within the same narrow band, because the role itself, not the outcome, is what the compensation structure is anchored to. This isn’t a flaw in how jobs work; it’s the actual design: a role has a market rate, and that rate moves slowly and generally in step with broader wage trends. In 2025, wages grew at approximately 3.3 per cent nationally, a figure that applies almost uniformly regardless of how much individual value a specific employee created that year. Why Business Income Isn’t Automatic Either It would be misleading to present business ownership as an automatic upgrade, and the same research that shows the upside is careful about the caveat. Gallup’s own report states plainly that entrepreneurship is a narrow pathway to wealth: being a business owner with no employees is not associated with significantly higher income, wealth, job satisfaction, or life evaluation compared to being an employee, and owner-employers make up just 2.4 per cent of all working adults in the US. A separate Forbes Advisor analysis of small business owner salaries found the average sits just 16 per cent above the national mean wage, a far smaller gap than the headline owner-employer numbers suggest. Job vs business income only tilts sharply in favour of the business when that business has actually scaled far enough to employ others and capture value beyond what one person’s labour alone can produce. The Dividing Line Is Scaling Value, Not Just Starting a Business The Gallup data draws a specific, important distinction that most popular narratives about entrepreneurship skip past. Operating a business and employing others are described in the research as meaningfully different stages rather than points along a typical progression, and the data backs that up structurally: fewer than 1 per cent of employees who tried transitioning to owner-employer status in 2023 had made that transition by 2025. Even among people who already owned a business without employees, only 5 per cent made that same jump in two years. The median age of an owner-employer business in the study is 19 years, compared to 7 years for self-employed workers, which suggests the income gap described above isn’t something that shows up quickly. It’s the result of a business sustaining and scaling its value creation over a long enough period that it can pay other people to help deliver it. Why the Gap Widens Further Through Equity, Not Just Income Job vs business income compounds differently over time for a reason that goes beyond the paycheck itself. Salaried income is almost entirely spent from or saved into standard accounts, while business ownership converts value creation directly into equity, an asset that can appreciate independently of any single year’s cash flow. High-net-worth entrepreneurs hold 27 per cent of their investment portfolio in private company equity, more than double the 11 per cent held by other high-net-worth investors, according to a 2026 survey of 233 individuals with an average net worth of $17 million. That equity concentration matters because business value, unlike a salary, can be built once and continue paying out or appreciating for years afterwards, closer to how an investment portfolio behaves than how a paycheck does. In the same period, wages grew roughly 3.3 per cent while the S&P 500 returned about 18 per cent, illustrating just how differently linear income and asset-based value creation actually compound. The Wellbeing Gap Is Part of the Same Pattern The financial gap isn’t the only measurable difference the Gallup research found, and the wellbeing data adds an important layer to why job vs business income matters beyond the number on a paycheck. Owner-employers reported meaningfully higher scores not just on income and net worth but on overall life evaluation and work engagement, a 19-point gap the researchers describe as one of the largest they’ve measured across working populations. The likely mechanism isn’t simply that owner-employers have more money; it’s that their income is directly tied to decisions they control and value they can see themselves creating, rather than being set by a role description negotiated once and adjusted incrementally from the outside. That sense of direct connection between effort and outcome shows up as a wellbeing effect independent of the income effect, even though the two clearly reinforce each other in the data. Who’s Actually Closing This Gap Right Now The population of people moving from job income to business income has been shifting in a way worth noting. Brookings research
Blog

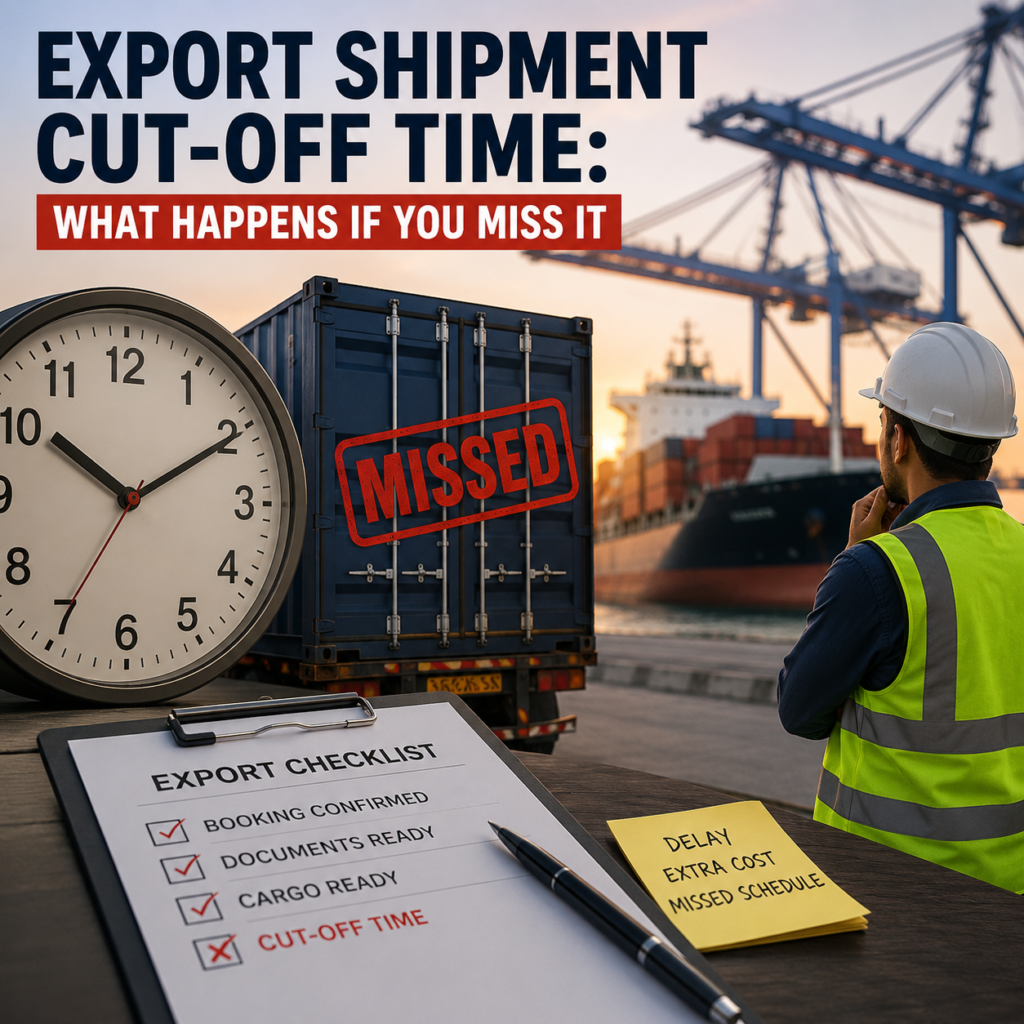
Export Shipment Cut-Off Time: What Happens If You Miss It

The goods are packed, the invoice is ready, the truck is booked, and the shipment still misses the vessel. An export shipment cut-off time isn’t one deadline; it’s a sequence of several separate ones stacked close together in the days before a ship departs, and missing any single link in that chain produces the same result: the container stays behind while the vessel it was booked on sails without it. The Five Deadlines Hiding Inside One ‘Cut-Off’ What most exporters think of as a single cut-off is actually a sequence of five separate deadlines, each controlled by a different party and each capable of stranding a shipment on its own. CY Open, usually around six days before the customs cut-off, marks the earliest the terminal accepts containers. The Shipping Instruction cut-off, typically 24 to 48 hours before departure, is the deadline to submit final bill of lading details. The VGM cut-off, the container’s verified weight, usually falls 6 to 12 hours before the physical closing time. The CY cut-off itself is the deadline for the loaded container to physically arrive at the terminal, generally 12 to 18 hours before the vessel berths. And a separate customs cut-off governs when declaration and clearance must be complete. Missing any one of these produces the same outcome regardless of how early the other four were handled. What Actually Happens: Rolled Cargo The industry term for a shipment that misses its export shipment cut-off time is rolled cargo, and the consequence is more disruptive than most exporters expect from what often started as a single missed deadline. A container that misses its cut-off gets rolled to the next available vessel, which typically means a delay of 7 to 14 days or more, depending on how frequently the carrier’s service calls at that port. For a buyer expecting delivery on a fixed schedule, that delay doesn’t stay contained to shipping. It cascades into missed retail windows, contractual penalty clauses, or a buyer simply sourcing the next order from a competitor who didn’t miss their sailing. The VGM Deadline Specifically Has No Flexibility Among the five deadlines, VGM stands apart because it isn’t a carrier policy that can be negotiated; it’s an international safety regulation. Under IMO SOLAS rules, the shipper listed on the bill of lading is legally responsible for submitting verified gross mass data, and if the terminal doesn’t have that VGM figure by the cut-off, the container cannot be loaded onto the vessel under any circumstances, regardless of relationship with the carrier or how far in advance everything else was ready. This exists for genuine safety reasons: an inaccurate or missing weight declaration affects a vessel’s stability and stowage plan, which is why terminal systems are built to lock out a container automatically rather than leave the decision to a dockworker’s judgment. Why the Cut-Off Sequence Exists in the First Place It’s worth understanding why these deadlines stack up the way they do, since the sequence isn’t arbitrary bureaucracy; it reflects the actual physical planning work a vessel requires before it can depart. A modern container ship can carry over 20,000 TEUs, and the ship planner responsible for stowage needs a finalised list of every container’s weight, contents, and hazard classification well before the vessel arrives at berth, in order to calculate weight distribution and stability across the entire hull. That planning process is what the CY cut-off is actually protecting: a terminal that kept accepting containers right up until departure would leave no time to finalise a stowage plan that keeps the ship safely balanced. Understanding the cut-off sequence as the visible output of that planning process, rather than an arbitrary administrative deadline, makes it easier to see why none of the five deadlines described above is treated as flexible by the terminal or the carrier. The Real Financial Cost of a Missed Cut-Off Beyond the relationship damage with a buyer, a rolled shipment carries a direct, quantifiable cost. A container sitting at a terminal waiting for its rescheduled sailing typically accrues storage charges, and once free time expires, demurrage charges commonly run 100 to 150 dollars per container per day, climbing past 250 dollars a day the longer the container sits, on top of whatever trucking or warehousing costs were already sunk into getting the container to the port in the first place. A shipment that missed its cut-off by a matter of hours can end up costing more in accumulated fees over a two-week rebooking wait than the shipping cost of the original booking. LCL Shipments Face an Earlier, Easier-to-Miss Deadline Exporters shipping less than a full container face a version of this problem that arrives earlier and gets overlooked more often. The Container Freight Station cut-off, the deadline for LCL cargo to reach the consolidation warehouse, sits well ahead of the FCL cut-off, since that cargo still needs to be inspected, grouped with other shippers’ goods, and loaded into a shared container before the CY cut-off applies to the consolidated box. An exporter used to FCL timelines who assumes an LCL shipment follows the same schedule frequently discovers the CFS deadline has already passed while they were still tracking the later FCL cut-off instead. Peak Season and Schedule Changes Make the Window Tighter The cut-off schedule quoted at the time of booking isn’t guaranteed to hold steady until departure. Cut-off times are tied to the vessel’s planned arrival, and if the carrier’s schedule shifts, whether from port congestion, a weather delay at a previous port of call, or a broader rerouting event affecting the vessel’s whole rotation, the cut-off times shift along with it, sometimes with only a day or two of notice. During peak shipping periods or around major holidays, carriers routinely tighten what’s normally a five-day standard cut-off window down to two or three days, giving exporters far less margin to correct a documentation error or a delayed truck than they’d have during a quieter month. An exporter who successfully hit every cut-off comfortably in one

Blog

Communication Skills in the AI Era: Why They Pay Off

AI can draft the email, summarise the meeting, and generate the report faster than any person at the table. What it still can’t reliably do is decide what actually needs saying, to whom, and in what tone, and that gap is exactly where communication skills in the AI era have quietly become one of the sharpest competitive advantages a professional can build, backed now by hiring data rather than just intuition. The Data Behind Communication Skills in the AI Era The scale of this shift shows up clearly in the largest datasets tracking hiring behaviour. LinkedIn’s 2026 Skills on the Rise report, drawing on data from over one billion profiles, found that soft skills now account for seven of the ten fastest-growing skills globally, with public speaking, conflict mitigation, and executive communication all landing in the top human-skills cluster. A separate 2026 hiring manager survey ranked communication as the single most valued soft skill overall. This isn’t a case of AI making communication less important by comparison. It’s the opposite: as AI absorbs more of the routine drafting and summarising work, the specific value of being able to communicate what actually matters has gone up, not down. There’s a real gap behind this demand, too. NACE’s Job Outlook 2026 survey found employers rated communication skills as important 98.7 per cent of the time, but only 55.4 per cent said recent graduates were actually proficient at it, a 43-point gap that shows the demand for communication skills in the AI era is running well ahead of the supply of people who can reliably deliver it. Why AI Made Communication More Valuable, Not Less The specific nature of communication work has shifted, and that shift is exactly what’s driving the premium. Hiring teams now routinely evaluate candidates on their ability to edit AI-generated output, push back on what’s wrong in it, and own the final version in their own voice, rather than purely on their ability to write a first draft from a blank page. A first draft is now cheap and instant. The judgment required to know when that draft is wrong, tone-deaf, or simply not the right message for a specific audience is not something current AI tools reliably supply on their own, and that judgment is precisely what separates someone who merely operates AI tools from someone who directs them well. This connects directly to a pattern showing up elsewhere in 2026 workplace research: employees are increasingly expected to explain, defend, and take ownership of AI-assisted work rather than simply forward it, and the ability to do that convincingly is itself a communication skill, not a separate technical one. A brilliant analysis buried in confusing language, or delivered without reading what a specific stakeholder actually needs to hear, still fails to land, regardless of how good the underlying AI-assisted work was. The Wage Premium Attached to This Shift The financial signal behind all this is measurable, and it’s grown fast. PwC’s 2026 Global AI Jobs Barometer, drawing on nearly a billion job postings, found the average wage premium for AI-skilled workers reached 62 per cent, and jobs requiring specific AI skills are growing almost eight times faster than the overall jobs market. The more telling detail sits inside that same report: AI-exposed entry-level roles are seven times more likely to require traditionally senior-level skills such as judgment and leadership than roles with less AI exposure, meaning the wage premium isn’t attached to technical AI fluency alone; it’s attached to technical fluency paired with exactly the human judgment and communication skills that separate a senior hire from a junior one. Entry-level workers are effectively being asked to communicate and judge like more senior employees earlier in their careers than before, precisely because AI has absorbed the routine execution work that used to fill that gap in experience. Where This Shows Up Across Different Industries The pattern isn’t confined to any single sector, and that breadth is part of what’s driving the wage data above. In technical fields, engineering, data science, software development, and communication have become the skill that decides whether a genuinely good piece of AI-assisted analysis actually changes a decision or simply sits in a report nobody acted on, since the technical work itself is increasingly commoditised by the same tools everyone else on the team has access to. In client-facing and sales roles, the ability to read what a prospect actually needs, rather than reciting an AI-generated pitch verbatim, has become the difference between a conversation that converts and one that reads as generic regardless of how polished the underlying material is. Even in fields built around routine documentation, healthcare administration, compliance, and financial reporting, the specific skill of explaining an AI-assisted finding to a regulator, auditor, or patient in plain, accountable language has become a distinct and separately compensated responsibility rather than an assumed extension of technical competence. What Being a Good Communicator Actually Means Now The skill itself has become more specific than the generic advice to write clearly. Being able to translate a technical result, a data finding, an AI-generated analysis, into language a non-technical stakeholder can act on has become a distinct and separately valuable skill, not an assumed byproduct of being technically competent. Conflict mitigation and stakeholder management, both explicitly named in LinkedIn’s 2026 fastest-growing skills data, matter more as AI removes some of the natural pauses and drafting time that used to force people to slow down and consider how a message would land before sending it. And executive communication, distilling something complex into a version a decision-maker can act on in thirty seconds, has become a specific, trainable skill that increasingly shows up as its own line item in hiring criteria rather than an assumed trait of anyone senior enough to be in the room. The Skills-Based Hiring Shift Reinforces This Trend This shift is reinforced by a separate, related change in how hiring itself works. NACE’s Job Outlook 2026 survey found that 70 per cent of employers now

Blog

Why Exporters Lose Money Even After Winning the Order

Landing the order feels like the hard part is over. The price is agreed, the buyer has confirmed, and the margin looked healthy on the spreadsheet the day the deal closed. Why exporters lose money on shipments that were priced correctly and sold at a fair rate rarely comes down to a single dramatic mistake. It comes down to a handful of costs that show up after the order is won and quietly eat the margin nobody priced into the quote. Currency Risk Eats the Margin Nobody Priced In A quote sent in dollars or euros locks in a price the day it’s issued, but payment often arrives weeks or months later, and the exchange rate rarely stays still. Peer-reviewed research published in 2026 on SME export performance found that exchange-rate volatility exerts a statistically significant negative drag on trade outcomes, with well-hedged firms able to neutralise or even reverse that drag, while unhedged firms absorb it directly as lost margin. Hedging isn’t automatically the fix either. Exporters who lock in a forward contract at the wrong moment can end up worse off than doing nothing at all: when a currency moves further than expected, a forward contract that looked like protection becomes a mark-to-market loss the exporter has to absorb regardless of how the underlying shipment performed. The Wire Transfer Itself Costs More Than Anyone Quotes Getting paid sounds like the finish line, but the payment rarely arrives at full value. World Bank data on international transfer costs found that bank-routed payments average 14.55 per cent in combined fees and exchange rate margin, compared to 3.55 per cent through digital-first platforms, a gap most exporters never see itemised on a single invoice. Part of that gap comes from correspondent banking specifically: on a standard SWIFT payment, each intermediary bank the payment passes through can deduct a lifting fee of roughly $15 to $50, and a wire an exporter expected to net in full can arrive several hundred dollars short with no warning about which bank took what. None of these deductions shows up on the buyer’s remittance advice. They simply reduce what lands in the exporter’s account. Demurrage and Detention: The Bill That Arrives After the Shipment Already Cleared This is where why exporters lose money becomes most visible, and most avoidable, since these charges are almost entirely about timing rather than bad luck. Demurrage and detention charges cost the global shipping industry an estimated 22 billion dollars a year, typically running 100 to 150 dollars per container per day and escalating past 250 dollars a day the longer a container sits, with a real-world case of 100 containers averaging a 600-dollar overrun producing a 60,000-dollar hit on a single shipment cycle. 2026 has made this risk sharper still: the Strait of Hormuz has been closed to container traffic since early March 2026, forcing major carriers to reroute cargo through alternate ports, and industry analysis found the resulting demurrage and detention exposure on delayed containers can run three and a half to seven times larger than the freight rate spike getting all the attention in the same period. An exporter can price a shipment perfectly and still lose the entire margin to a port delay that has nothing to do with the product, the buyer, or the price agreed. Compliance Errors Turn Into Financial Losses Weeks Later A shipment can clear customs without incident and still cost an exporter money discovered only later. An HS or HSN code that’s technically defensible but imprecise can mean a lower RoDTEP or duty drawback rate than the exporter assumed when pricing the deal, a gap that never triggers a red flag because nothing about the shipment itself was rejected. Missing the FEMA export realisation window, a deadline that has shifted between 9 and 15 months across recent RBI amendments, converts a completed, profitable-looking sale into a formal compliance issue with its own penalty exposure, layered on top of whatever margin the shipment already lost to currency movement or port delays. Quality Claims and Disputes Chip Away at the Same Margin A shipment that clears customs cleanly and reaches the buyer on schedule can still cost an exporter money through a channel unrelated to logistics or currency: a post-delivery quality claim. Buyers who identify a defect, a shortfall in quantity, or a mismatch against the agreed specification after goods have already been paid for or are due for payment often negotiate a deduction directly off the invoice rather than initiating a formal returns process, since shipping goods back across a border is rarely worth the cost for either side. These deductions are typically framed as reasonable and are often difficult to dispute cleanly once the shipment has already left the exporter’s direct control, which makes them one of the least visible line items behind why exporters lose money on paper-profitable orders. A quality control step that costs a few hundred dollars before a container is sealed is consistently cheaper than a deduction negotiated after the buyer has already taken possession and lost the incentive to be flexible. Insurance gaps compound this risk further. A shipment insured only for the value declared on the commercial invoice, without accounting for freight and duty already paid, can leave an exporter under-covered by exactly the difference between those two figures if the cargo is damaged or lost in transit. Reviewing what a policy actually covers, rather than assuming a generic marine insurance policy covers the full landed cost, is a five-minute check that prevents a total loss from becoming a partial, unrecoverable one. Why Winning the Order Was Never the Same as Keeping the Margin Every cost described above shares one trait: none of it shows up on the invoice the exporter sends the buyer. The quoted price, the agreed Incoterm, and the signed purchase order all look final the day the deal closes, but the actual profit on that order isn’t determined until the currency has converted, the wire has landed, the container has cleared

Blog

Creative Thinking in Design: What Grabs Attention

Most visuals lose their audience before anyone consciously decides to look away. Creative thinking in design isn’t really about taste or talent as much as it’s about understanding a handful of things neuroscience and eye-tracking research have established about how attention actually gets captured, held, or lost in the first fraction of a second, and building a visual around those mechanics rather than around personal preference alone. Why Attention Is a Battle Won or Lost Instantly The timeline involved is faster than most designers assume. A landmark MIT study led by neuroscientist Mary Potter found the human brain can identify the concept of an image after seeing it for as little as 13 milliseconds, far faster than the 100 milliseconds previously assumed necessary. That finding means the core impression a visual makes, whether it registers as interesting, relevant, or safe to ignore, happens before a viewer has consciously processed a single detail. This is where creative thinking in design earns its keep: a visual built around one clear focal point gives that 13-millisecond window something specific to latch onto, while a cluttered layout forces the brain to guess, and guessing usually loses. The Colour Science Behind What Gets Noticed First Colour isn’t a matter of pure preference either, and 2026 eye-tracking and ad-performance data is fairly specific about what actually works. The highest-performing ads in 2026 maintain a text-to-background contrast ratio of at least 7 to 1, and eye-tracking research consistently shows that high-saliency colors like bright red or yellow attract the first fixation faster and more often than muted or low-contrast palettes, a pattern researchers call attentional capture. There’s a specific trap worth naming here too: gradient backgrounds, a dominant visual trend through 2024 and 2025, show mixed results in eye-tracking studies, since they look appealing but can blur where a viewer’s eye is actually supposed to land, while solid backgrounds with a single deliberate colour accent consistently perform better for anything meant to drive a specific action. Visual Hierarchy Decides What Gets Seen Second and Third Grabbing the first fixation only solves part of the problem, since almost every real visual- a slide, a poster, a social post- needs a viewer to move on to a second and third piece of information rather than stopping at the headline alone. This is where visual hierarchy, the deliberate order in which elements are designed to be noticed, does the work that raw attention-grabbing alone can’t. Design researchers describe this as a layered system: contrast pulls the eye first, but size, colour saturation, and spatial position then determine the sequence everything else gets noticed in, whether that sequence is planned deliberately or happens by accident. A page without a designed hierarchy still has one. It’s just being decided by whatever accidentally has the strongest contrast, which is rarely the actual headline or call to action a designer intended to lead with. One consistent finding worth building into any layout is what researchers describe as a U-shaped salience curve for grayscale value: dark elements stand out most strongly against a light background, and light elements stand out most strongly against a dark one, with mid-tones in either direction reading as comparatively passive regardless of colour. Applied practically, this means a call-to-action button in a mid-saturation colour on a similarly toned background will lose the attention battle to a competing element with sharper light-dark contrast, even if the CTA is technically the more important piece of the design. Novelty Beats Familiarity, But Only Within Limits Contrast alone doesn’t fully explain what pulls a viewer’s eye. A well-controlled 2020 visual attention study found that novelty and saliency actually compete for gaze, and a genuinely new or unexpected element can draw attention even when it isn’t the most visually loud thing on the page, since the visual system is tuned to notice what breaks a pattern it has already learned to expect. This is the research backbone behind why the same layout, colour scheme, or template used repeatedly across a feed or a campaign gradually loses its pull. The brain isn’t reacting to the visual quality dropping. It’s reacting to the pattern becoming familiar enough that novelty detection stops firing. This cuts both ways, though. An industry-wide swing toward the same trend, the current wave of highly saturated dopamine colours across fashion, beauty, and lifestyle branding being one clear example, eventually produces the opposite of the intended effect once every competitor adopts it: when everything looks novel in the same way, nothing does. Analysts covering this trend are already predicting a version of colour fatigue by late 2026 for exactly this reason. Motion and Dynamic Elements Change the Math For anything shown on a screen rather than printed, movement adds a variable static design can’t compete with. A controlled 2026 eye-tracking study on commercial poster design found that dynamic, animated versions of the same poster significantly outperformed static versions on both total fixation duration and total fixation count, a statistically strong result across sixty participants. That doesn’t mean every visual needs animation. It means a static design has to work harder to hold attention than a moving one gets closer to automatically, which is exactly why a still image competing against video content in the same feed needs a stronger, more deliberate focal point to have any chance. Why This Matters More on Mobile Than It Used To The stakes around all of this have risen specifically because of where most visuals actually get seen now. A phone screen gives a design a fraction of the space a poster or a print ad used to have, and it competes for attention against autoplay video, notifications, and an endless scroll rather than a relatively static environment. Eye-tracking research on mobile advertising consistently finds that the window to earn a second look shrinks further on a small screen, since a thumb can scroll past a flat, low-contrast design in well under a second, before the 13-millisecond recognition window has even had a chance to translate into

Blog

Good Salary vs Financial Stability: Why They Differ

A six-figure income looks, on paper, like the finish line for financial worry. Good salary vs financial stability turns out to be a much weaker relationship than most people assume, and 2025 and 2026 survey data show high earners running out of money before the next paycheck at rates that would surprise anyone who thinks of income and stability as roughly the same thing. The Data Behind Good Salary vs Financial Stability The clearest evidence comes from a major retirement and income survey. The Goldman Sachs 2025 Retirement Survey and Insights Report, based on responses from over 5,100 people, found that about 40 per cent of workers earning more than $300,000 a year said they live paycheck to paycheck, a rate close to that of the lowest income group surveyed. A separate 2026 analysis found something even more counterintuitive: Americans earning $100,000 a year are now more likely to report living paycheck to paycheck than those earning $50,000, a reversal of what income alone would predict. Good salary vs financial stability isn’t a straight line upward. Past a certain point, more income stops automatically buying more breathing room. What ‘Survival Mode’ Actually Looks Like at $200K The discomfort at high income levels isn’t just a self-reported feeling with no real consequences behind it. Among households earning at least $200,000, 60 per cent report feeling like they’re in survival mode, and some in that group have delayed paying bills or postponed medical care specifically because of cost, according to 2026 research from SoFi. A 2025 Harris Poll found a similar pattern from a different angle: roughly one in three Americans with six-figure incomes reported experiencing genuine financial distress within the past year. None of this means high earners are struggling the way a minimum-wage household is. It means the specific feeling of running close to the edge financially shows up at income levels most people assume are well past that risk. Lifestyle Inflation Is the Mechanism Behind the Number There’s a well-documented behavioural pattern that explains most of this gap: lifestyle inflation, sometimes called lifestyle creep, where spending rises in step with income until the raise stops producing any actual financial cushion. A new car replaces the old one, a bigger apartment replaces the smaller one, and small upgrades that each felt reasonable in isolation add up to a budget with no more slack at $250,000 than it had at $90,000. Financial commentators covering this pattern consistently point to the same fix: building a budget anchored to a prior, lower income level even after a raise arrives, so the difference between old and new earnings actually accumulates as savings rather than disappearing into upgraded spending before anyone notices it happened. High-Income Debt Looks Different, But Isn’t Automatically Safer One nuance is worth adding, honestly, since the picture isn’t uniformly grim at the top. High-income households carry the largest credit card balances in raw dollar terms, but at a debt-to-income ratio typically well under 2 per cent, compared to a household earning under $25,000 carrying a debt-to-income ratio on credit cards alone that can run above 16 per cent. In that narrow sense, debt genuinely is more manageable at higher income. But manageable debt-to-income math doesn’t automatically translate into savings or a cushion, which is exactly the disconnect the paycheck-to-paycheck data above captures: the math can look fine on a spreadsheet while the actual bank balance stays thin. Why Income Alone Doesn’t Predict How Someone Handles Money Part of what makes this pattern counterintuitive is that most financial advice implicitly assumes income is the constraint, that the real problem is simply not earning enough. The data above suggests the constraint is often behavioural rather than mathematical once income clears a basic threshold. A household earning $60,000 that has built a habit of saving a fixed percentage before spending anything else will often weather an unexpected expense more comfortably than a household earning $200,000 that has never built that habit, simply because the second household’s entire budget, including bills that scale with the higher income, absorbs the full paycheck by design. This is really the heart of good salary vs financial stability as a distinction: financial planners who work with high-income clients report this pattern often enough that it has its own informal name in the industry, sometimes called HENRY, standing for High Earner, Not Rich Yet, describing exactly this gap between income and accumulated wealth. This isn’t an argument that income doesn’t matter, since a higher income obviously makes building savings easier in absolute terms when the habit is actually in place. It’s an argument that income and financial behaviour are two separate variables, and treating a raise or a high salary as automatically solving financial stability skips the step where the actual saving has to happen deliberately, not by default. The Emergency Fund Gap Cuts Across Every Income Level The clearest single measure of financial stability, an emergency fund, shows the same story from yet another direction. Bankrate’s 2026 Emergency Savings Report found that 27 per cent of US adults have zero emergency savings, 59 per cent couldn’t cover a $1,000 emergency expense from savings alone, and 29 per cent carry more credit card debt than they have set aside in savings. None of these figures is broken out as exclusively low-income problems, and the paycheck-to-paycheck data above confirms why: a household earning $250,000 with no consistent savings habit is structurally in the same position as a household earning $60,000 with the same habit, just with a larger number attached to the shortfall when an emergency actually arrives. What Actually Builds Stability, Beyond Just Higher Income The practical fix isn’t complicated to describe, even though it’s genuinely difficult to sustain once a lifestyle has already expanded to match an income. Closing the gap between good salary vs financial stability starts with treating a raise as partially invisible, routing a meaningful share of it directly into savings or investments before it ever reaches a checking account, which prevents the slow creep

Blog

HS Code vs HSN Code: The Real Difference Explained

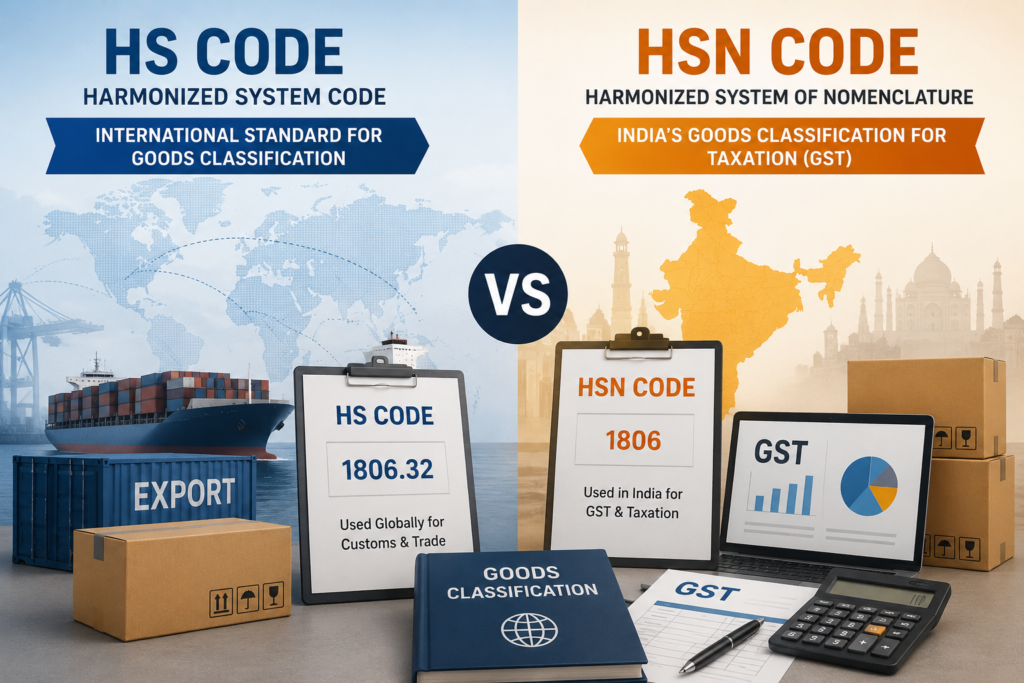
The two terms are used interchangeably so often that most businesses assume they’re the same thing, and, in a loose sense, they are. But HS code vs HSN code isn’t just a naming quirk. One is the global classification standard every WCO member country recognises. The other is India’s specific, extended application of that same standard for GST, and mixing the two up on an invoice or a shipping document is one of the most common, and most costly, compliance mistakes exporters and GST-registered businesses make. HS Code vs HSN Code: Same System, Different Name Both terms trace back to the same origin. The Harmonised System was developed by the World Customs Organisation and has been in force since January 1, 1988. It’s now used by more than 200 countries and customs territories, covering over 98 per cent of global merchandise trade. HS is the term used internationally, in shipping documents, customs declarations, and trade agreements worldwide. HSN, short for Harmonised System of Nomenclature, is simply India’s name for its own implementation of that same system, used specifically under the GST framework for domestic tax classification. Functionally, they’re the same numbering logic. Administratively, they answer to different authorities and different rules. The Real Difference Is in the Digits This is where HS code vs HSN code actually starts to matter in practice. The global HS code is 6 digits: the first two identify the chapter, the next two the heading, and the final two the subheading, a structure that stays identical across every WCO member country. India extends this. An Indian HSN code runs to 8 digits, with the first six matching the international standard exactly and the final two forming an India-specific tariff item used for finer GST rate and duty classification. A product like a laptop, for instance, shares the same 6-digit subheading with a laptop classified anywhere else in the world, but its full 8-digit Indian HSN code narrows that down to the exact tariff line that decides the GST rate applied domestically. Where Each Term Actually Gets Used The two terms aren’t just synonyms swapped at random; they show up in genuinely different documents. HS, or its Indian customs variant ITC-HS, governs the Directorate General of Foreign Trade’s export and import policy, and it’s what appears on a shipping bill or a bill of entry when goods physically cross the border. HSN governs GST compliance specifically, appearing on tax invoices, GSTR-1 returns, and e-way bills for domestic transactions. A business that only sells within India will mostly deal with HSN in a GST context. An exporter deals with both, since customs paperwork uses the ITC-HS framing while domestic invoicing for the same product uses the HSN framing, even though the underlying 8-digit number is identical either way. A Worked Example: Following One Product Through Both Systems Working through an actual product makes the digit structure easier to hold onto than the abstract chapter-heading-subheading explanation alone. Take a cotton knitted t-shirt. Under the international HS system, it falls under chapter 61, the broad category for knitted apparel, narrowed to heading 6109 for t-shirts specifically, and further narrowed to subheading 610910 at the six-digit level, the point where every WCO member country’s classification converges on the same number. India then appends its own two-digit extension to reach the full 8-digit HSN, distinguishing, for instance, cotton t-shirts from t-shirts made of other fibres within that same heading, a level of detail that exists purely for Indian tariff and GST purposes and has no equivalent requirement in most other countries. The same logic applies to less obvious products. Basmati rice sits under chapter 10 for cereals, heading 1006 for rice broadly, subheading 100630 for semi-milled or wholly milled rice, and only becomes distinctly identifiable as basmati specifically at the 8-digit Indian tariff item. A business shipping semi-milled rice internationally can rely on the global 6-digit code being understood identically by a buyer’s customs authority anywhere in the world. The same business filing a domestic GST invoice for that same shipment needs the full Indian-specific 8-digit code to get the correct GST treatment, because the international six digits alone leave room for more than one applicable Indian tariff line. How Many HSN Digits a GST Invoice Actually Needs This part trips up more businesses than the classification itself. Under CBIC Notification 78/2020, businesses with turnover up to ₹5 crore need to report a minimum 4-digit HSN code on B2B invoices, businesses above ₹5 crore must report 6 digits, and exports and imports require the full 8-digit code regardless of turnover. Since January 2025, HSN-wise reporting in Table 12 of GSTR-1 has been mandatory for every taxpayer, and the portal now validates codes from a fixed list rather than accepting free text, which means a code that used to slip through as a minor typo now gets rejected outright at filing. What Happens When You Get the Code Wrong The consequences aren’t symbolic. An invoice carrying the wrong HSN code can shift a product into the wrong GST slab entirely, and under Section 31, an inaccurate HSN code on an invoice means the buyer’s input tax credit claim can be denied, turning a classification error on the seller’s side into a cash flow problem on the buyer’s side. For businesses inside the e-invoicing threshold, an invalid or incomplete HSN code can also cause the Invoice Reference Number to be rejected, which leaves the invoice legally invalid until it’s corrected and re-filed. On the export side, using the wrong ITC-HS code carries a separate risk: RoDTEP and duty drawback refund rates are tied directly to the HSN classification, so an imprecise code can quietly cost an exporter money every month without triggering any obvious red flag. Don’t Just Copy a Supplier’s or Buyer’s Code A habit worth breaking early: treating a code that arrives on a supplier’s invoice or a buyer’s purchase order as automatically correct for your own filing. Classification responsibility sits with whoever is issuing the invoice or making the

Blog

HS Codes Explained: Why One Digit Changes Everything

A shipment can have the right buyer, the right price, and perfect paperwork everywhere else, and still get held at port over a single number. HS Codes Explained simply: it’s a classification code, not a formality, and getting it wrong doesn’t just risk a delay. It can change the duty owed, cancel a refund an exporter was counting on, or trigger a formal penalty, and 2026 enforcement data show this is happening to many more shipments than most exporters assume. What an HS Code Actually Is The Harmonised System is a global classification standard maintained by the World Customs Organisation, and every traded product gets sorted into it by material, function, or composition rather than by brand name or marketing description. The first six digits of an HS code are standardised worldwide, organised into chapters, headings, and subheadings, and this six-digit core stays identical whether a shipment is headed to the US, Germany, or Vietnam, with no major global revision scheduled until 2027. Classification itself isn’t a judgment call left to guesswork. It follows the WCO’s General Rules of Interpretation, along with legally binding Section Notes and Chapter Notes that specify exactly how borderline products should be classified. Why India Adds Two More Digits India, like most countries, extends the global six-digit code with national digits for its own tariff and trade policy needs. Indian customs requires the full 8-digit ITC-HS code for every declaration, with the final two digits, the tariff item, carrying the specific detail that determines Indian duty rates and trade policy treatment, distinct from the six digits recognised internationally. A supplier’s invoice from overseas often only lists the international six-digit code, which leaves an Indian exporter or importer responsible for adding the correct final two digits themselves, and this exact gap is where a large share of classification errors actually originate. The Real Cost of Getting One Digit Wrong The financial swing from a single digit is larger than most exporters expect. A one-digit difference in an ITC-HS code can shift a product from duty-free to a 10 per cent tariff overnight, directly changing the landed cost calculation a buyer was quoted. India’s tariff schedule also draws sharp lines within a single product category: fabrics are classified differently above and below a 200 GSM weight threshold, and an assembled printed circuit board can fall under an entirely different chapter depending on whether customs determines it functions as a component or a finished product, each with different duty treatment and different regulatory notification requirements attached. Penalties Under the Customs Act, and How Severe They Get Indian customs enforcement doesn’t treat classification errors as routine clerical mistakes anymore. Section 114 of the Customs Act allows a penalty of up to three times the duty differential for misdeclaration, meaning a 1.5 lakh rupee duty gap alone can produce a penalty of 4.5 lakh rupees, before the underlying duty itself is even paid. Section 112 adds a separate penalty ranging from 10,000 rupees up to the full value of the goods, and where misclassification is judged deliberate, Section 111 permits outright confiscation of the goods, with a redemption fine of 10 to 25 per cent of the goods’ value required even where confiscation itself is avoided. Recent data cited by trade compliance platforms suggests nearly one-third of all customs declarations in India currently contain some form of classification error, which gives a sense of how exposed the average exporter actually is. The Refund That Disappears Quietly The financial damage from a wrong HS code isn’t limited to fines and back duty. Misclassification invalidates RoDTEP and duty drawback refund claims retroactively, meaning an exporter who classified at the wrong subheading for months can lose every refund tied to those shipments, not just the ones caught by a customs audit going forward. Since RoDTEP rates themselves vary by HS classification, a code that’s technically defensible but imprecise, four digits deep instead of the full eight, can also mean an exporter is simply leaving money on the table every single month without ever triggering a penalty or a red flag. This Isn’t Only an Indian Problem Exporters shipping into other major markets face a parallel version of the same risk. US Customs and Border Protection can fine importers up to 20 per cent of declared value for negligent classification errors, rising to 40 per cent or more in cases treated as reckless or fraudulent, and repeated errors can trigger CBP’s Focused Assessment program, a sustained audit cycle rather than a one-time penalty. A recurring misconception makes this worse across every market: many exporters assume a supplier’s declared HS code is automatically correct for the destination country, when in practice HS codes frequently diverge at the national digit level, and legal responsibility for the declaration sits with the importer or exporter of record, not the supplier who first suggested the code. What Gets Flagged Beyond the Duty Itself A wrong HS code creates operational friction well beyond the immediate financial hit. Under India’s automated risk management system, a shipment linked to a past classification error is more likely to get routed for physical examination rather than automated clearance on future filings, adding days to every subsequent shipment rather than just the one that triggered the review. Customs authorities in 2026 increasingly treat repeated misclassification, even when individually minor, as a governance failure rather than a series of unrelated clerical slips, which shifts how a business gets treated on every future filing, not just the flagged one. That reputational shift is often harder to reverse than the original penalty, since it changes the default assumption customs makes about every future shipment from that exporter rather than resolving with a single payment. Certain product categories carry an added layer of risk that makes accurate classification even more consequential. Chemical exports classified under an organic compounds chapter instead of the correct miscellaneous chemical products chapter, for instance, can inadvertently overlap with restricted or dual-use goods lists, turning a duty dispute into a much more serious compliance

Blog

Personal Financial Risk in Business: What Changes

A business plan reads the same whether it’s funded by a bank’s money, an investor’s money, or a founder’s own savings. The decisions made under that plan don’t. Personal financial risk in business changes how people evaluate spending, hiring, and slow months, and 2026 data on how small businesses are actually funded shows just how many owners are operating with exactly that kind of exposure, often without fully realising how much. Most Owners Already Have More Personal Exposure Than They Think The idea of a business as a separate financial entity, cleanly walled off from an owner’s personal finances, doesn’t match how most small businesses are actually financed. According to the Federal Reserve’s 2025 Small Business Credit Survey, released in March 2026, 59 per cent of firms with outstanding debt used a personal guarantee to secure it, and 51 per cent pledged business assets as collateral. A personal guarantee means exactly what it sounds like: if the business can’t pay, the lender can pursue the owner’s personal assets, not just whatever the business itself owns. SBA and USDA-backed loans go further still, requiring a full personal guarantee from any owner holding a 20 per cent or greater stake in the business, as a standard condition of approval rather than a negotiable term. Startup capital tells a similar story. 58 per cent of small businesses in the US start with less than $25,000, and roughly a third start with less than $5,000, funding that overwhelmingly comes from personal savings rather than outside investment. Separate research from SoFi found that only 18 per cent of women business owners used a business or SBA loan to launch, meaning the large majority financed their start with personal money instead. Personal financial risk in business isn’t a hypothetical for most owners. It’s the default starting condition. Why Personal Money Changes the Actual Decisions There’s a well-documented behavioural reason the source of the money matters, not just the amount. Research on loss aversion consistently finds that people evaluate risk differently when the money at stake is their own versus someone else’s, generally treating personal losses as more painful than equivalent gains feel good, a bias that softens noticeably when the money on the table belongs to someone else. This is part of why founder-led companies in a widely cited study of S&P 500 firms from 1993 to 2003 generated 31 per cent higher citation-weighted patent performance, a measure of genuine innovation impact, compared to companies run by professional managers without an ownership stake. Skin in the game doesn’t just change caution. It changes commitment, time horizon, and what an owner is willing to personally sacrifice to keep something working. The flip side is real too, and worth naming honestly. Owners with too much personal exposure sometimes hold onto a failing decision longer than the numbers justify, because walking away feels like admitting a personal loss rather than a business one. Personal financial risk in business sharpens judgment in most cases, but it can also make it harder to cut losses at exactly the moment cutting losses is the right call. The Legal Structures That Actually Limit Exposure The single biggest lever most owners underuse is entity structure. Operating as a sole proprietorship, still common among freelancers and very small operations, offers no legal separation at all between business debts and personal assets. Forming an LLC or a private limited company creates that separation on paper, but a personal guarantee on a loan effectively overrides that protection for that specific debt, regardless of how the business is legally structured, which is why the guarantee itself, not just the entity type, is the real determinant of personal exposure. Reading exactly what’s being guaranteed, and for how long, before signing a business loan matters more than the entity structure sitting underneath it. Some personal guarantees can be negotiated down rather than accepted as written. Lenders will sometimes agree to a guarantee capped at a percentage of the loan, a guarantee that expires after a set number of on-time payments, or a carve-out that excludes a primary residence specifically. None of this is offered automatically. It has to be asked for, and it’s far easier to negotiate before signing than to renegotiate after a business hits a rough patch and the lender has less incentive to be flexible. Where the Risk Shows Up Beyond the Loan Itself Loans and guarantees get most of the attention, but they’re not the only place personal money quietly ends up exposed. Credit cards used to cover a cash flow gap between invoicing and getting paid are personal liability by default unless a business card is specifically structured and used correctly, and many small business owners run both personal and business expenses through the same card without realising the legal and tax consequences of blending the two. Vendor contracts and commercial leases often carry their own personal guarantee clauses buried in the fine print, separate from anything a bank requires, and landlords leasing commercial space to a new business routinely ask for one as standard practice rather than a special request. A 2026 StartupNation analysis of commercial lending trends found that delinquency rates on small business loans climbed steadily through 2024 and 2025, driven by higher interest rates and tighter cash flow margins, which has made lenders and landlords alike more insistent on personal guarantees rather than less. The direction of that trend matters for anyone assuming personal guarantees will become less common as their business grows: right now, the opposite is true. Health insurance, retirement contributions, and even personal credit scores are indirect but real forms of exposure too. A founder who stops paying themselves a salary to keep the business afloat during a rough stretch isn’t just making a business decision; they’re making a personal financial one with consequences that show up on a personal balance sheet long after the business decision is forgotten. Personal financial risk in business rarely arrives as one dramatic signature on a loan document. It usually accumulates

Blog

AI vs Human Explanation of Work: Why It Matters

Ask an AI tool to write the report, fix the code, or draft the pitch, and it will hand back something polished in seconds. Ask the person who submitted that work to explain why it’s structured that way, what assumption it’s built on, or what happens if one input changes, and the answer often falls apart. AI vs human explanation of work has quietly become one of the sharpest tests in offices, classrooms, and interview rooms in 2026, and a growing stack of research suggests a lot of people would fail it. The Interview Question That Exposes This Directly The clearest, most literal version of this test now happens in job interviews themselves. Meta began rolling out AI-enabled coding interviews in late 2025, handing candidates an assistant like Cursor, Copilot, or Claude Code instead of a blank editor, and companies including Shopify, Rippling, LinkedIn, Canva, and Uber have adopted similar formats through 2026. The AI is allowed and expected. What’s being graded isn’t whether the candidate can produce working code; it’s whether they can direct, verify, and explain it. The failure pattern shows up consistently across these interviews: at Canva, interviewers pause after each AI generation and ask candidates to walk through what the code does, and a Rippling candidate was explicitly rejected for relying too heavily on AI even though their initial approach was correct, because they let the AI make the implementation decisions instead of directing them. Getting the right answer stopped being the bar. Being able to explain and defend the answer became the actual bar. Botshitting: Shipping Work You Can’t Defend There’s now a specific term for the pattern this creates outside interview rooms, too. A 2026 report from Glean found that nearly 7 in 10 AI users admit to what researchers call botshitting, shipping AI-generated work they haven’t reviewed, don’t fully understand, or couldn’t defend if asked, with heavy AI users, Gen Z employees, men, and managers most likely to do it. The same report found digital workers now spend nearly a full workday every week botsitting, checking outputs, debugging mistakes, and fixing confidently wrong answers, a workload that itself seems to be pushing people toward skipping the review step entirely rather than adding more of it. When the Work Fails, Who Actually Takes the Blame The gap between doing the work and explaining it has a psychological cost that researchers can now measure directly. When AI-generated work fails, 40 per cent of workers blame the AI, while only 29 per cent admit it was their own fault, a pattern researchers describe as moral disengagement, the gradual process by which people stop holding themselves accountable for outcomes they had a hand in. A related Boston Consulting Group experiment found something that makes this worse rather than better: when AI was framed as an employee rather than a tool, workers felt less accountable for what it produced and reviewed its output less carefully. The more AI gets treated like a colleague, the less anyone feels obligated to explain what it actually did. The Accountability Gap Shows Up at the Company Level Too This isn’t only an individual habit problem. It’s showing up in how organisations track their own AI-generated output. Lanai’s 2026 AI Labour Report found that 92 per cent of leaders say their organisation tracks the financial and efficiency impact of AI-generated work, but only 2 per cent say more than half of that work is actually recorded as a measurable business outcome, a pattern researchers call AI labour orphaning. Separately, Grant Thornton’s 2026 AI Impact Survey found that 78 per cent of business executives lack strong confidence they could pass an independent AI governance audit within 90 days. If leadership can’t reconstruct how an AI system reached a decision, asking an individual employee to explain and defend it becomes an almost impossible position to put them in. Frontline Workers Are Explaining Decisions They Didn’t Make A July 2026 Harvard Business Review study, based on multi-year fieldwork across banking, recruitment, and biotechnology, found that frontline employees are increasingly expected to communicate, justify, and defend AI-generated decisions they neither created nor fully understand. The researchers found workers respond in one of three ways: they relay the AI’s output verbatim without really owning it, they mask it by presenting it as their own reasoning even when it isn’t, or they amplify and complement it by adding genuine judgment on top. Only the third pattern actually closes the gap between AI vs human explanation of work in any meaningful way, and it’s also the pattern that takes the most deliberate effort to practice. The Same Pattern Is Showing Up in Classrooms This isn’t strictly a workplace phenomenon either. The interview trend at Meta, Canva, and Rippling has a direct parallel in how universities and bootcamps have started grading assignments: rather than banning AI outright, instructors increasingly allow it and then grade the student’s ability to walk through and defend what the tool produced, on the logic that this is now the actual skill being hired for. Reports from hiring managers running technical interviews describe a consistent tell: a candidate who produces an optimal solution unusually quickly but can’t walk through even one worked example, or fails when asked pointed questions about specific lines of their own submitted code. Several interviewers have said plainly that when a candidate can’t explain their own logic, it doesn’t matter whether AI was involved or not: the explanation gap alone is the disqualifying factor. How to Actually Close the Gap None of these point toward using AI less. It points toward a specific habit that’s easy to skip under deadline pressure: before submitting anything AI-assisted, being able to state in one or two sentences why it’s structured the way it is, what it assumed, and what would break if a key input changed. That single check is close to what Canva’s interviewers are actually testing for, and it’s the difference between directing a tool and simply forwarding its output. Teams that build

Scroll to Top